
Published 2 November 2026 · By Jatin Dua, Broker of Record, RE/MAX Quantum Realty
What's Your Home Worth Right Now?
Get a free AI-powered price range for your property in under 90 seconds, based on recent GTA comparable sales. No name or address required.
Get My Free Estimate →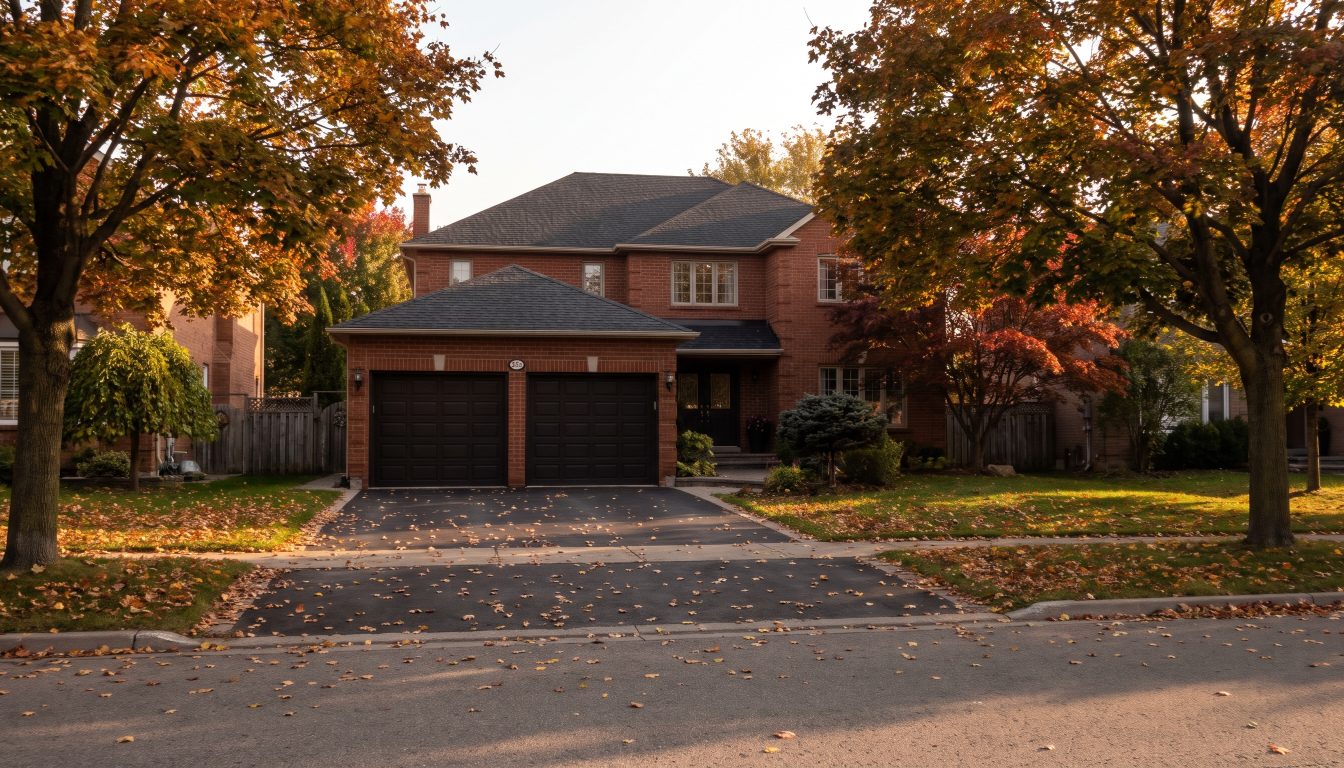
In 2027, $2 million buys a typical detached house in every GTA city, including Oakville, King and Richmond Hill, and in most Toronto districts. It falls short only in midtown and central pockets such as Leaside, Lawrence Park, the Annex, Rosedale and the Bridle Path. You need at least $400,000 down and roughly $360,000 of household income.
This guide is for move-up buyers, growing families and relocating professionals with about $2 million to spend in Toronto and the GTA in 2027. You will see where that budget bought a typical detached house in 2026, where it still falls short, and the cash and income a $2 million purchase really takes.
What can you buy for $2 million in the GTA in 2027?
At $2 million, you are shopping in the top 6% of the GTA market. Across the TRREB area, 94% of all homes sold from January to October 2026 went for less than that. Your realistic options are:
- A typical or better-than-typical detached house in every GTA municipality, from Oakville and King to Markham, Vaughan and Richmond Hill.
- A typical detached house in most Toronto districts, including High Park-Swansea, the Junction and Bloor West Village, the Beaches, Riverdale, Forest Hill South and Yonge-Eglinton, Willowdale East and the Kingsway area.
- A semi or freehold townhouse in almost any part of Toronto, including the Annex, Lawrence Park and Leaside.
- A large luxury condo anywhere in the GTA.
What $2 million does not reliably buy is a detached house in Leaside, Mount Pleasant, Lawrence Park, the Annex and Casa Loma, Rosedale or the Bridle Path, where 2026 medians were above it.
How many GTA homes sell for over $2 million?
Fewer than a year ago. TRREB’s October 2026 Market Watch shows 3,043 homes sold for $2 million or more from January to October 2026, or 5.8% of all sales. In the same months of 2025 it was 3,349, or 6.2%.
| Home type | Sales at $2M+, Jan–Oct 2026 | Share of that type | Sales at $1.5M–$1.99M | Sales at $2M+, Jan–Oct 2025 |
|---|---|---|---|---|
| Detached | 2,688 | 10.9% | 3,297 | 2,998 |
| Semi-detached | 126 | 2.6% | 314 | 114 |
| Condo apartment | 162 | 1.2% | 195 | 170 |
| Freehold townhouse | 46 | 0.9% | 133 | 40 |
| Condo townhouse | 19 | 0.5% | 48 | 21 |
| All home types | 3,043 | 5.8% | 3,995 | 3,349 |
Source: TRREB Market Watch, October 2026 and October 2025, sales by price range and house type, year to date (all TRREB areas). Shares are my calculation. “All home types” also includes link, co-op and detached condo sales.
The detached market is where the action is. About 89% of detached houses sold for under $2 million in 2026, so a $2 million buyer can afford roughly nine in ten of them.
Where does $2 million buy a typical detached house?
These are the GTA cities and Toronto districts with detached medians between $1.4 million and $2 million from January to October 2026. In each one, your budget covers more than half of the market. Everywhere else in the GTA, the median was lower still, apart from downtown C01 and C08, which had only 57 and 5 detached sales.
| Area (sample communities) | Detached median | Change vs 2025 | Avg. days on market | Sales |
|---|---|---|---|---|
| King | $1,850,000 | −9.1% | 47 | 150 |
| Toronto W01 (High Park-Swansea, Roncesvalles) | $1,850,000 | −7.5% | 16 | 111 |
| Toronto C03 (Forest Hill South, Yonge-Eglinton) | $1,793,000 | −4.4% | 24 | 223 |
| Toronto C14 (Willowdale East, Newtonbrook East) | $1,691,900 | −6.0% | 36 | 174 |
| Toronto W02 (Junction Area, Runnymede-Bloor West Village) | $1,637,500 | −1.1% | 14 | 194 |
| Oakville | $1,625,000 | −3.0% | 33 | 1,162 |
| Toronto E02 (The Beaches, East End-Danforth) | $1,613,000 | −9.6% | 16 | 144 |
| Toronto W07 (Stonegate-Queensway) | $1,548,000 | +6.8% | 19 | 140 |
| Toronto W08 (Kingsway South, Princess-Rosethorn) | $1,540,000 | −7.8% | 24 | 440 |
| Toronto E01 (North and South Riverdale) | $1,515,000 | −2.9% | 14 | 109 |
| Toronto C13 (Banbury-Don Mills, Parkwoods-Donalda) | $1,515,000 | −2.6% | 26 | 155 |
| Richmond Hill | $1,485,000 | −8.9% | 31 | 838 |
| Toronto C07 (Willowdale West, Lansing-Westgate) | $1,445,000 | −6.8% | 32 | 209 |
| Markham | $1,420,000 | −6.5% | 29 | 1,113 |
| Vaughan | $1,415,000 | −5.0% | 30 | 1,193 |
Source: TRREB MLS data via REALM, January–October 2026 vs the same period of 2025. City and Toronto district medians and average days on market only, not neighbourhood prices. Community names from TRREB’s Q2 2026 community reports.
Oakville is the biggest pool by far, with 1,162 detached sales and a median $375,000 below your budget. In Markham, Vaughan and Richmond Hill, $2 million moves you well above the typical house, often into newer and larger homes. For a waterfront take on the same budget, see what $2 million buys on the GTA waterfront.
Where is $2 million not enough for a detached house?
Six central Toronto districts had detached medians above $2 million in 2026:
- C10 (Mount Pleasant East and West): $2,125,000
- C11 (Leaside, Thorncliffe Park, Flemingdon Park): $2,258,500
- C04 (Lawrence Park, Bedford Park-Nortown, Forest Hill North): $2,352,500
- C02 (Annex, Casa Loma, Yonge-St. Clair, Wychwood): $2,375,000
- C12 (Bridle Path-Sunnybrook-York Mills, St. Andrew-Windfields): $3,200,000
- C09 (Rosedale-Moore Park): $3,627,500
In the first four, $2 million can still buy a smaller or older detached house, or a semi. The 2026 semi median was $1,713,500 in C02 and $1,641,250 in C04, and Leaside’s district (C11) had a semi median of $1,380,000. In C12 and C09, $2 million is usually a condo or townhouse budget. My list of the most expensive Toronto districts for detached homes covers these markets.
Free tool — what can you actually afford?
How much cash do you need to buy a $2 million home?
At least $400,000 down. Mortgage insurance is only available on homes priced under $1.5 million, so at $2 million you must put down 20%. The good news is that with 20% down there is no insurance premium and no sales tax on one.
| $2,000,000 purchase, repeat buyer | Outside Toronto | City of Toronto |
|---|---|---|
| Minimum down payment (20%) | $400,000 | $400,000 |
| Ontario land transfer tax | $36,475 | $36,475 |
| Toronto land transfer tax | none | $36,475 |
| Cash needed before legal fees | about $436,500 | about $473,000 |
| Monthly payment at 4.75%, 30 years | $8,302 | $8,302 |
| Monthly payment at 4.75%, 25 years | $9,079 | $9,079 |
Source: my calculations from CMHC’s $1.5 million insurance limit, Ontario and City of Toronto land transfer tax rates as of November 2026. The 4.75% rate is illustrative; uninsured rates are usually a little higher than the lowest insured five-year fixed rate of 4.44% (Ratehub, 9 November 2026).
Watch the $2 million line. Above it, Ontario’s rate on homes with one or two single-family residences rises from 2% to 2.5%, and Toronto’s municipal rate also rises to 2.5% up to $3 million. Inside Toronto, every dollar over $2 million costs 5 cents in land transfer tax instead of 4. At $2.2 million, the combined Toronto bill is $82,950. My post on land transfer tax on a luxury home works through higher prices.
What income do you need for a $2 million house in Toronto?
About $362,000 of household income, on my assumptions, with $400,000 down, a 30-year uninsured mortgage at 4.75% and no other debts. Here is the math.
- Loan: $1,600,000.
- Stress test: for uninsured mortgages at federally regulated lenders, OSFI requires you to qualify at the higher of 5.25% or your rate plus 2 points, so 6.75% here.
- Housing costs counted: the qualifying payment of about $10,279 a month, property tax (I assumed 0.8% of price, about $1,333 a month) and heat ($150 a month), which must fit within 39% of gross income.
Thirty-year amortizations on uninsured mortgages are at the lender’s discretion. On 25 years, the income needed rises to about $383,000. Putting $500,000 down instead lowers it to about $342,000. Real property tax depends on your city’s rate and your MPAC assessment, so check the actual bill on any house you like.
Will you face bidding wars at $2 million?
It depends heavily on where you look. TRREB’s year-to-date figures for all home types show two very different markets in 2026:
- Fast and competitive: homes in Toronto E02 sold for 105% of list price on average, W02 for 104% and W01 for 102%. Detached houses there sold in 14 to 16 days on average.
- Slow and negotiable: homes in Toronto C12 sold for 92% of list price on average, King for 94%, Rosedale’s C09 for 95% and Oakville for 96%. King’s detached houses took 47 days on average.
In the west and east end, $2 million often means competing on a well-priced house that was listed low to draw offers. In King, Oakville and north Toronto, it usually means a slower negotiation where conditions and a lower price are realistic. For a side-by-side of two very different ways to spend this budget in the city, see High Park-Swansea or Yorkville.
Does $2 million buy more in 2027 than it did in 2024?
Yes. Several areas where $2 million was a stretch in 2024 are now comfortably within reach. Detached medians, January to October 2024 vs 2026:
- Toronto C14 (Willowdale East): $2,160,000 to $1,691,900
- King: $2,120,000 to $1,850,000
- Toronto C01 (downtown): $1,890,000 to $1,500,000
- Richmond Hill: $1,774,400 to $1,485,000
- Toronto C02 (Annex, Casa Loma): $2,812,500 to $2,375,000
Borrowing costs rose in late 2026, though. The Bank of Canada raised its policy rate to 2.50% on 28 October 2026, its first increase in more than three years, and said it could raise again if needed. At this loan size, each 0.25-point rise adds roughly $230 to $240 a month to a 30-year payment.
At $2 million, your biggest choice is not the house, it is the market you shop in. A slow area like Oakville or King lets you negotiate and keep conditions, while the Junction or the Beaches may force you to bid firm. Decide which trade-off you can live with first. I would also keep at least three months of payments in reserve after closing, given where rates are heading.
Many detached houses in Toronto’s older districts are decades old. Budget for a full inspection, including a sewer camera scan, and ask about past additions and permits. A wet basement or failed drain can cost tens of thousands of dollars, and it is easier to find before you firm up than after.
What to do next
- Confirm your down payment of at least $400,000 plus land transfer tax, and keep it in accessible accounts.
- Get an uninsured pre-approval and ask whether the lender offers 30 years.
- Choose between a fast, competitive area and a slower, negotiable one before you book showings.
- Compare recent sales on the same street, not just the district median.
- Book an inspection, sewer scan and permit search before you go firm.
Need help with this? Talk to me.
I’m Jatin Dua, Broker of Record at RE/MAX Quantum Realty, and I’m the best agent to do this kind of work for you in Toronto and across the GTA. Over $100 million in GTA sales and 100+ families helped sell. Feel free to contact me any time: call or text 833-330-1925 or email [email protected].
Frequently asked questions
What can I buy for $2 million in Toronto?
In Toronto, $2 million buys a typical detached house in most districts in 2027, including High Park-Swansea, the Junction, the Beaches, Riverdale, Forest Hill South, Willowdale East and the Kingsway area. It buys a semi in the Annex or Lawrence Park. It falls short of the detached median in Leaside, Mount Pleasant, Lawrence Park, the Annex, Rosedale and the Bridle Path.
How much down payment do I need for a $2 million house in Ontario?
You need at least $400,000, or 20%, to buy a $2 million house in Ontario. Mortgage insurance is only available on homes priced under $1.5 million, so lower down payments are not allowed at this price. With 20% down you pay no insurance premium, but you still need cash for land transfer tax and legal fees.
What income do I need to buy a $2 million home in the GTA?
About $362,000 of household income to buy a $2 million home with $400,000 down, a 30-year mortgage at 4.75% and no other debts, by my November 2026 estimate. The stress test qualifies you at 6.75%. On a 25-year mortgage you need about $383,000, and with $500,000 down about $342,000.
How much is land transfer tax on a $2 million house in Toronto?
Land transfer tax on a $2 million house in Toronto is $72,950: $36,475 to Ontario and $36,475 to the City of Toronto, as of November 2026. Outside Toronto you pay only the $36,475 Ontario tax. Above $2 million, both rates rise to 2.5% on the extra amount for homes with one or two single-family residences.
How many homes sold for over $2 million in the GTA in 2026?
3,043 homes sold for $2 million or more across the TRREB area from January to October 2026, or 5.8% of all sales, per TRREB’s October 2026 Market Watch. Detached houses made up 2,688 of them. In the same months of 2025, 3,349 homes sold at that level, or 6.2% of sales.
Is $2 million enough for a house in Oakville?
Yes. Oakville’s median detached price was $1,625,000 from January to October 2026, per TRREB data via REALM, so $2 million buys more than half of the town’s detached market. Oakville had 1,162 detached sales in that period, homes took 33 days to sell on average, and buyers paid 96% of list price overall.
Which GTA city has the most expensive detached homes?
King had the highest detached median of any GTA municipality at $1,850,000 from January to October 2026, followed by Oakville at $1,625,000. Inside Toronto, Rosedale-Moore Park (C09) was highest at $3,627,500, then the Bridle Path and St. Andrew-Windfields district (C12) at $3,200,000, per TRREB data via REALM.
Do $2 million homes sell over asking in Toronto?
In some districts, yes. In 2026, homes of all types sold for 105% of list price on average in Toronto E02 (the Beaches) and 104% in W02 (the Junction, Bloor West Village), per TRREB. In C12 (the Bridle Path area) the average was 92%, and in King 94%, so buyers there usually negotiate below asking.
Can I get a 30-year mortgage on a $2 million house?
Often, yes. At $2 million you need an uninsured mortgage with at least 20% down, and lenders may offer 30-year amortizations at their discretion. Insured mortgages, where 30 years is limited to first-time buyers and new builds, are not available at this price. A longer amortization lowers the payment but adds interest over time.
Sources
- TRREB Market Watch, October 2026
- TRREB Market Watch, October 2025
- CMHC: CMHC Purchase ($1.5 million limit, GDS and TDS)
- OSFI: Minimum qualifying rate for uninsured mortgages
- Ontario: Calculating land transfer tax
- City of Toronto: MLTT and MNRST rates and fees
- Ratehub: 5-year fixed mortgage rates (checked 9 November 2026)
- Bank of Canada: Policy rate announcement, 28 October 2026
Related reading
- Biggest Condo Developers in Toronto: Track Records Buyers Should Check
- Is It a Good Idea to Buy a Condo in Toronto in 2027?
- Buying a House in Ontario on a Work Permit (2027): What the Foreign Buyer Ban Allows
- Can You Buy a House With No Down Payment in Ontario?
About the author — Jatin Dua, Toronto and GTA real estate broker
I am Jatin Dua, Broker of Record and co-founder of RE/MAX Quantum Realty Inc., Brokerage, Unit 101, 799 The Queensway, Toronto. I work with buyers and sellers across Toronto and the GTA and have helped more than 100 families sell. Four-plus years of active GTA transactions and over $100 million in sales volume.
Reach me at [email protected] or 833-330-1925, or book a call.