

Published 25 September 2026 · By Jatin Dua, Broker of Record, RE/MAX Quantum Realty
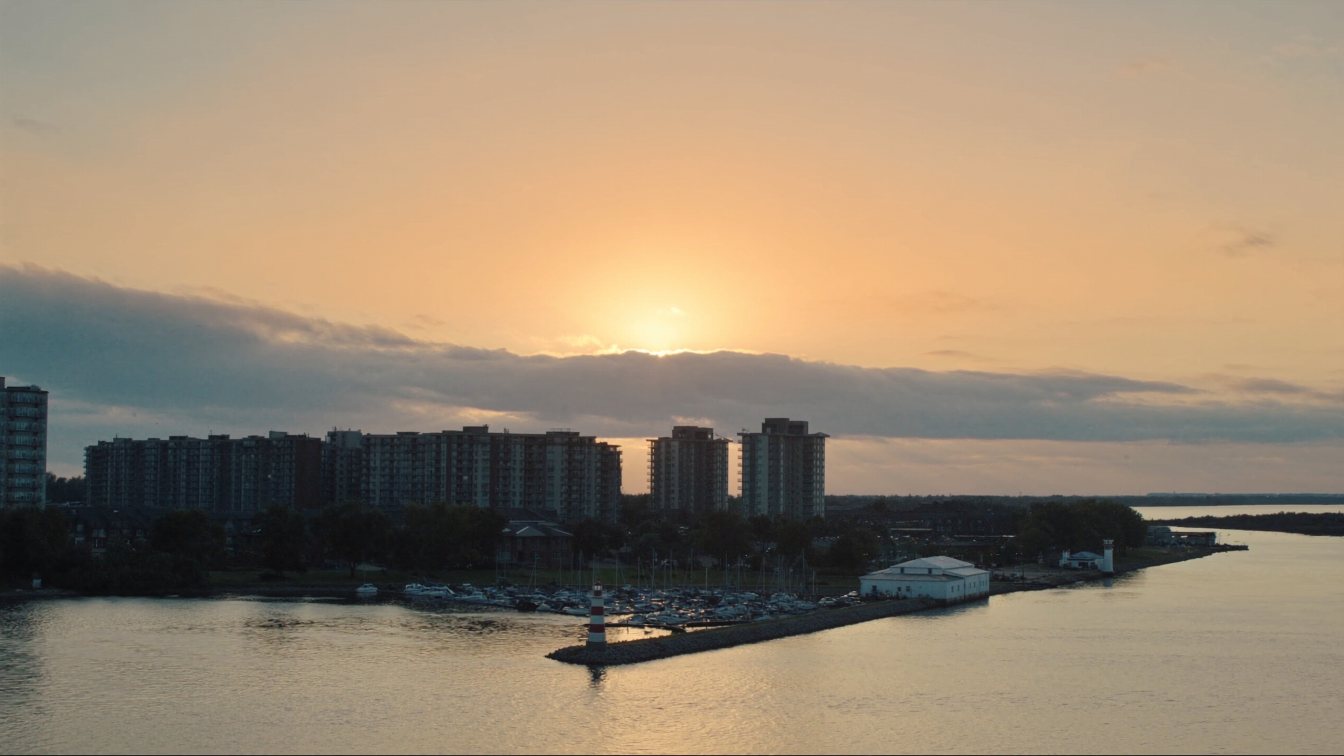
Port Credit is Mississauga’s only true waterfront village: a GO station on the Lakeshore West line, a working harbour at the mouth of the Credit River, and a short main street of independent shops. Condo stock splits into three zones — the older lakefront towers east of the river, the village core along Lakeshore Road, and the two master-planned sites now under construction, Brightwater (2,995 homes) to the west and Lakeview Village (16,000 homes) to the east. Prices vary by zone, view and age far more than by the name Port Credit itself. Check the status certificate, ask what the reserve fund has done in the last five years, and treat the Hurontario LRT as a bonus with no opening date, not a reason to pay more today.
Where Port Credit actually is, and what counts as waterfront
Port Credit sits where the Credit River meets Lake Ontario, roughly between Mississauga Road on the west and the Lakeview neighbourhood on the east, with Lakeshore Road West as its spine. The GO station is a five-minute walk from the harbour, which is the single fact that keeps demand steady when the rest of Mississauga’s condo market softens.
Not every “Port Credit condo” sees the lake. Listings use the name loosely for anything from Lakeshore Road south to the water and, increasingly, for buildings a kilometre north near the Queen Elizabeth Way. Before you get attached to a unit, put the address into a map and check three things: which side of Lakeshore Road it sits on, whether anything can be built between it and the water, and how far the walk to the GO platform really is on foot rather than as the crow flies.
The three condo zones
It helps to think in zones rather than in building names, because a zone tells you what you are paying for.
| Zone | What it is | What you are buying |
|---|---|---|
| Lakefront east of the river | Older towers on the water from the 1990s and 2000s | Unobstructed lake views, larger suites, higher fees, older mechanical systems |
| Village core | Mid-rise and boutique buildings on or near Lakeshore Road | Walk-to-everything convenience, smaller suites, street noise on the main road |
| Master-planned sites | Brightwater (west, 72 acres) and Lakeview Village (east, 177 acres) | New construction, years of adjacent building, a neighbourhood that does not fully exist yet |
The same 700 square feet can be priced very differently across these three zones. That is not the market being irrational. It is the market pricing view, age, fees and certainty separately, which is exactly what you should do.
What Brightwater and Lakeview Village change
Two projects will add more homes to the Port Credit shoreline in the next decade than exist there today. Brightwater, on the old Imperial Oil refinery lands at Lakeshore and Mississauga Road, is planned at 2,995 residences with 300,000 square feet of retail and a new elementary school. Lakeview Village, on the former power station site to the east, was rezoned in May 2023 to 16,000 units with first occupancy expected in early 2029.
For a buyer today that cuts two ways. Resale owners in the existing towers gain a much larger, busier neighbourhood with more shops and parks, and an eventual pier the City describes as the longest on the Great Lakes. They also face a decade of construction traffic and a large volume of brand-new competing supply when they eventually sell. Neither effect is certain in size. Both are certain in direction.
Transit: the GO station is real, the LRT is not open
Port Credit GO is on the Lakeshore West line with frequent service to Union. That is the transit fact that matters for value and it has been true for decades.
The Hazel McCallion Line, the 18-kilometre light rail line from Port Credit GO north to Brampton Gateway, is under construction. As of April 2026 Metrolinx had not announced an opening date. Listings that describe a unit as “steps from the LRT” are describing a future. Pay for what is running today. If the line opens while you own, that is upside you did not buy.
Fees, reserve funds and the age problem
The lakefront towers east of the river are the buildings most people picture when they say Port Credit. Many are now 20 to 30 years old. That is the age at which windows, balcony membranes, garage slabs and elevators come due, and the age at which reserve funds either prove adequate or do not.
Before you offer on any building in that zone, read the status certificate and the most recent reserve fund study together. You want to see the fund growing on a plan, not a special assessment in the last three years and not a fee increase well above inflation without a stated reason. Waterfront buildings also carry weather costs that inland buildings do not: wind-driven rain on the lake face, salt spray on lower balconies and glazing that takes more punishment. Ask specifically whether the window and balcony work has been done, is scheduled, or is not yet in the study.
What sells, and what sits
- Sells: south-facing suites with an unobstructed lake view, two-bedroom layouts over 900 square feet in the older towers, parking included, low-rise buildings with elevators that work.
- Sits: north-facing suites in lakefront towers (you pay the building’s fees without its view), studios and small one-bedrooms in buildings with high fixed fees, anything where the status certificate shows a live special assessment.
- Watch: units whose view depends on a neighbouring parcel that is zoned for something taller. In a neighbourhood adding thousands of homes, “protected view” means very little unless the water is in front of you.
How I would price a Port Credit condo today
I start with the building, not the neighbourhood. Sales in the same building over the last twelve months, adjusted for floor and exposure, tell you more than any Mississauga-wide average. Where a building has had no sales, the next best comparison is the same zone and the same decade of construction, not the shiny new tower down the road.
Then I subtract for what the status certificate reveals and add only for what is physically permanent: the water in front, the GO station within walking distance, a layout that does not waste space. I do not add for planned transit or for the eventual promenade. When those arrive, the market will price them. You do not need to do it in advance with your own money.
The takeaway
Port Credit is a good place to own a condo because of the GO station, the water and the village, all of which exist today. Buy in the zone that matches what you want to pay for, read the reserve fund study before the floor plan, and treat the LRT and the two mega-projects as things that might make you money later rather than reasons to spend more now.
Where I fit
I work across Toronto and the GTA and sell on both sides of the Etobicoke–Mississauga border. If you are weighing Port Credit against Humber Bay Shores or Long Branch, I can show you what the same money buys in each on the same afternoon, and tell you which buildings I would not put a client into. Run your current condo through the estimator below to see what you are working with, or book a call.
Free tool — AI condo value estimator
Condo Valuation
What’s your condo
worth today?
Three quick steps. Condos don’t price like houses — your floor, your view, and whether you own parking move the number more than anything else. This weighs all of them.
Reading recent condo sales…
Estimated market value
—
$0–$0
Most likely $0 · about $0 per square foot
What moved the number
Starting from what comparable units in your area sell for, here’s what your specifics added or subtracted.
Market context
—
—
Two units, same floor plan,
$90,000 apart.
That happens constantly in condos — one has the parking, the right exposure, or a board that keeps the reserve fund healthy. A model can’t see your status certificate. I can.
Frequently asked questions
Is Port Credit a good place to buy a condo in 2026?
It is one of the more defensible condo locations in Mississauga because the GO station, the harbour and the village exist today rather than on a rendering. The risk is age in the older lakefront towers and a decade of construction from Brightwater and Lakeview Village. Buy the building, not the postcode.
Which Port Credit condos have real lake views?
Only the towers on the water east of the Credit River and a handful of buildings on the south side of Lakeshore Road. Anything north of Lakeshore sees the lake only from upper floors, and only until something is built in between. Check the zoning of the parcel between the unit and the water.
How much are maintenance fees in Port Credit condos?
Fees vary by building age and amenities and I do not publish a per-square-foot figure because no verified source exists for it. Older lakefront towers with pools and 24-hour concierge run higher; small mid-rise buildings in the village run lower. Compare the fee to what it includes, and read the reserve fund study.
When does the Hurontario LRT open at Port Credit?
As of April 2026 Metrolinx had not announced an opening date for the Hazel McCallion Line. It is under construction. Do not pay a premium for it today.
What is Brightwater in Port Credit?
A 72-acre master-planned community on the former Imperial Oil refinery lands at Lakeshore Road West and Mississauga Road, planned for 2,995 condos and townhomes, 300,000 square feet of retail and office, a new elementary school and an 18-acre park system. The partners are Kilmer Group, DiamondCorp, Dream Unlimited and FRAM + Slokker.
What is Lakeview Village in Mississauga?
A 177-acre redevelopment of the former Lakeview power station site on Mississauga’s eastern waterfront, rezoned in May 2023 for 16,000 residential units with more than 45 acres of parkland. The first building, Harbourwalk, began construction in October 2024 and first occupancy is expected in early 2029.
Should I buy a resale Port Credit condo or wait for the new projects?
It depends on what you want. Resale gives you a known building, a known view and a known fee today. Pre-construction gives you a newer suite and years of waiting, interim occupancy and the risk of delay. If you need to live somewhere in the next two years, resale is the only real option.
Sources
- City of Mississauga — Lakeview Village project page (updated 17 July 2026) — site size, unit count, first occupancy
- Kilmer Group — Bringing new homes to Port Credit’s waterfront — Brightwater site, partners, unit count
- Metrolinx — Hazel McCallion Line — route and construction status
- Global News, 31 March 2026 — Hurontario LRT and fare integration — no official opening date
- TRREB Market Watch, August 2026 — GTA market context
Related reading
- What $600,000 buys on the GTA waterfront
- The Mississauga waterfront at every budget
- Mineola, Port Credit and Lakeview Houses
- Lorne Park Lakefront Homes
- Top 10 things no one tells you about Port Credit
- Brightwater Port Credit: what buyers should know
- Lakeview Village: what is actually being built
- Humber Bay Shores vs Mimico
- Buying a 20-year-old waterfront condo
About the author — Jatin Dua, Toronto and GTA real estate broker
I am Jatin Dua, Broker of Record and co-founder of RE/MAX Quantum Realty Inc., Brokerage, Unit 101, 799 The Queensway, Etobicoke. I work with buyers and sellers across Toronto and the GTA, with deep local knowledge of the west end and the Lake Ontario shoreline. Four-plus years of active GTA transactions and over $100 million in sales volume. Every market figure here comes from TRREB’s published tables and every rule from the regulator or the legislation, so you can check all of it without asking me.
Reach me at connect@jatindua.com or 833-330-1925, or book a call.