
Published 2 November 2026 · By Jatin Dua, Broker of Record, RE/MAX Quantum Realty
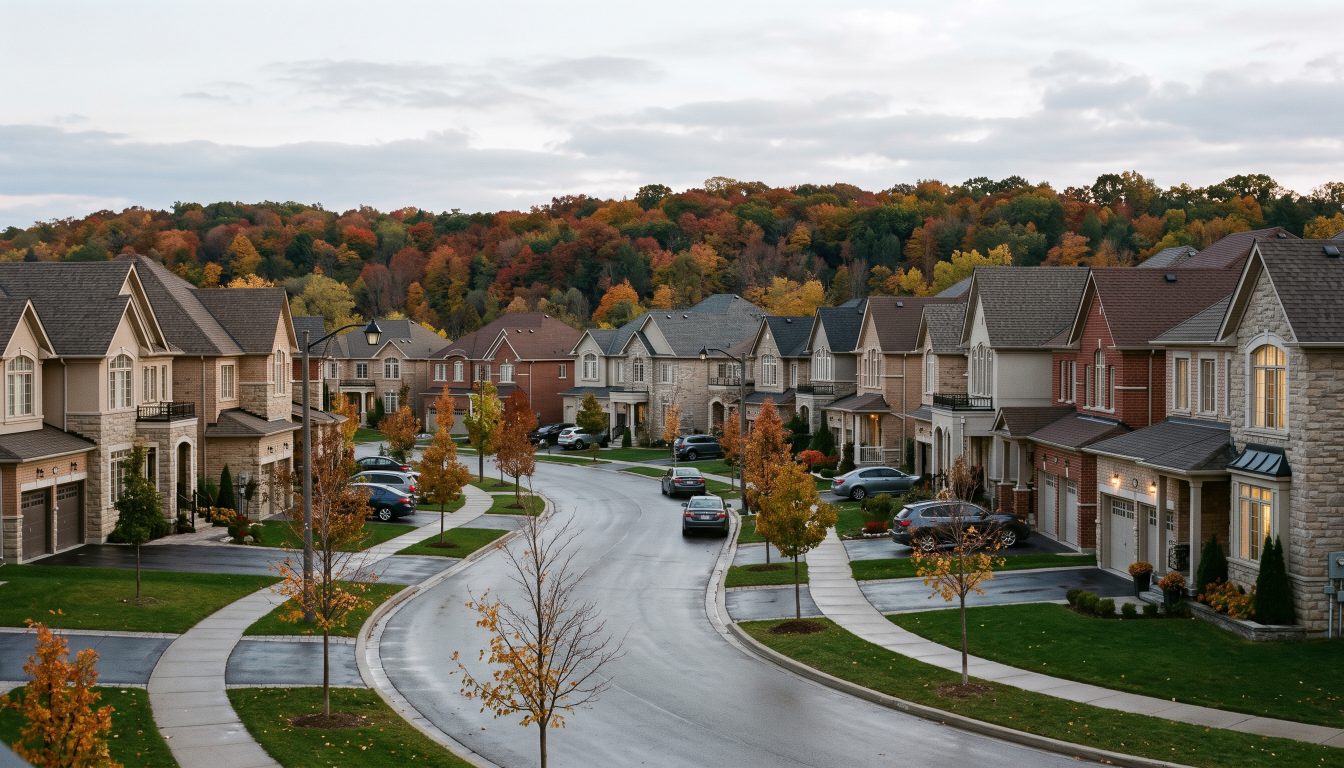
The best realtor in Credit Valley for 2027 compares your home with sales of similar lot frontage, knows the City’s updated Credit Valley plan, and checks river, creek and second-unit rules. Brampton’s detached median fell 8.9% to $950,000 (Jan–Oct 2026) while sales rose 9%, so ask for written pricing evidence and negotiate the fee.
This guide is for Credit Valley homeowners who may sell in 2027 and for buyers looking at houses in west Brampton. You will get verified Brampton price numbers, what the City’s updated plan for Credit Valley says about lots and new building, the river and creek rules that affect some streets, the questions to ask an agent and the red flags to avoid.
Where is Credit Valley in Brampton?
Credit Valley is one of Brampton’s planned communities, with its own secondary plan. Under Brampton’s new Official Plan, the old Credit Valley Secondary Plan (Area 45) was replaced with a new one, now numbered Area 12. The City’s September 2026 consolidation describes the area this way:
- Size: about 1,176 hectares (2,907 acres) in southwest Brampton.
- Boundaries: Mississauga Road and the Credit River to the west, Steeles Avenue West and the CPR tracks to the south, Chinguacousy Road to the east, and Bovaird Drive and the CNR tracks to the north.
- Wards: parts of City Wards 4 and 5.
- Natural features: the Credit River, Huttonville Creek and Springbrook Creek, plus Eldorado Park and the scenic Creditview Road, which the plan names as key parts of the community’s character.
The plan says low-rise housing of up to three storeys is the main form of building here, with a built form that fits the area’s countryside character. Taller buildings are directed to the main roads, as explained below.
What are Brampton home prices doing heading into 2027?
There is no reliable public median for Credit Valley alone, and I will not make one up. Here is the verified picture for Brampton, including how far prices have moved in two years. Use it as context, not as a price for your street.
| Brampton home type | Median, Jan–Oct 2026 | Change vs 2025 | Change vs 2024 | Sales, Jan–Oct 2026 |
|---|---|---|---|---|
| Detached | $950,000 | −8.9% | −15.7% | 2,280 |
| Semi-detached | $790,000 | −8.1% | −14.4% | 687 |
| Freehold townhouse | $755,000 | −7.2% | −13.4% | 554 |
| Condo townhouse | $570,000 | −10.9% | −16.3% | 237 |
| Condo apartment | $415,000 | −12.6% | −23.1% | 241 |
Source: TRREB MLS data via REALM, January–October 2026 vs the same periods of 2025 and 2024. City of Brampton as a whole, not Credit Valley alone. Medians, not forecasts.
City-wide, the detached median is down about 15.7% from 2024. But detached sales rose 9% this year, which tells me buyers are active at today’s prices. In October 2026 alone, TRREB reported 249 detached sales in Brampton at a median of $922,500, and homes took an average of 27 days to sell. All home types in Brampton had about 4.6 months of inventory that month, which gives buyers time to compare.
The Bank of Canada raised its policy rate to 2.50% on 28 October 2026, and big-bank prime moved to 4.70%. For a single home’s value, see how much your Brampton house is worth.
What does “Upscale Executive Housing” mean for Credit Valley prices?
Parts of Credit Valley are designated for Upscale Executive Housing. The plan sets out what that means:
- Mainly detached homes, with a limited number of high-end semis and townhouses where the design is strong.
- A minimum lot frontage of 15 metres (50 feet), with a range up to 26 metres (85 feet) and beyond.
- “Anchor” areas with frontages of 21 metres (70 feet) or more, meant to give these enclaves their distinct feel.
- A maximum density of 14.8 units per net residential hectare.
For pricing, this means frontage is not a detail. A 70-foot lot in an anchor area and a much narrower lot a few streets away are different products, and a fair comparison has to match them. When an agent shows you comparable sales, ask for the lot frontage of each one.
Frontage is only part of the story. Buyers in this part of Brampton also weigh what the lot backs onto, whether it sits on a quiet crescent or near a busy road, the size and finish of the house, and how the basement is set up. A strong pricing report lists each of those for every comparable sale and explains the adjustments in plain numbers. If two agents give you very different prices, ask both to show their comparables side by side. The gap usually comes from one agent ignoring lot size or backing, and that is easy to spot once the details are on one page.
Instant Home Valuation
What’s your home
worth today?
Answer six quick questions and get an instant value range built from current Toronto & GTA sale data — property type, size, condition, lot and location all weighted the way a real pricing conversation weighs them. Takes about ninety seconds.
Reading recent GTA sale data…
Building your estimate
Estimated market value
—
$0–$0
Most likely value $0 · roughly $0 per square foot
What moved the number
Starting from the area baseline for your property type, here’s what each answer added or subtracted.
Market context
Recent local averages for comparison.
—
A range is a starting point.
A strategy is what sells.
This model doesn’t know that your neighbour’s identical semi went $80,000 over asking last month, or which two upgrades actually pay back in your area. That conversation is free and takes twenty minutes.
What is changing in Credit Valley that buyers and sellers should watch?
The updated plan allows more height on the main roads:
- Queen Street West is a “Primary Urban Boulevard,” where four-storey low-rise plus and mid-rise buildings of 5 to 12 storeys are permitted.
- Mississauga Road, Chinguacousy Road and Bovaird Drive West are corridors where mid-rise buildings are permitted.
- James Potter Road and Williams Parkway are support corridors where four-storey low-rise plus housing is permitted.
Some land is not settled. The City’s consolidation notes that parts of the plan are under appeal at the Ontario Land Tribunal, including lands tied to the Lionhead Golf Course. The plan says that when the golf use ends, the valleyland is to be dedicated to the City, which also has a right of first refusal if the course is sold.
Along Springbrook Creek, insauga reported in 2019 that planning near Queen Street West and Creditview Road was paused for years over environmental concerns, including the redside dace, a fish found in Springbrook Creek. The plan for that pocket aims to keep a small, hamlet-like character.
If you are buying next to one of these sites, ask your agent what has been approved, what is only proposed, and where to find the City’s planning notices for updates.
What should a Credit Valley realtor check on lots near the river and creeks?
Credit Valley is named for the Credit River, and water shapes some lots. Credit Valley Conservation is the conservation authority for the Credit River watershed. Before you plan a pool, addition or garden suite on a lot near the river or a creek, ask whether the lot is regulated and what permits apply. My guide to building on conservation-regulated land explains how to check.
The plan also singles out the historic Eldorado Mills area along the Credit River as a special policy area with a rural, countryside streetscape. Much of it is designated Natural System, and parts lie within the regional floodline.
Brampton does not allow additional residential units in floodplain areas or open space zones. If you are paying extra for a lot near the river because you plan to add a basement apartment or garden suite, confirm the rules for that exact property first, and make your offer conditional if you need to. “Backs onto the valley” is a selling point, not a building permit.
What should you know about second units and rental licences in Credit Valley?
Brampton allows up to three units on a property, counting the main house, and every additional unit must be registered with the City. That includes older units once treated as legal non-conforming. The City lists a minimum $1,000 fine for an unregistered unit.
Brampton’s residential rental licensing program, updated on 1 January 2026, requires owners renting one to four units to hold an annual licence. Applications are free, but landlords need $2 million in liability insurance and must complete an online education module. If you are selling a rented home, have the licence and unit registration ready for buyers.
What questions should you ask a Credit Valley realtor before hiring?
- Which recent sales are you comparing my home to, and what were their lot frontages?
- Is my street in an Upscale Executive Housing area, and how does that affect value?
- Is my lot near the river or a creek, and have you checked whether it is regulated?
- What is planned on Queen Street West or the corridors near me, and how might buyers react?
- If my home has a second unit, what proof of registration will you show buyers?
- What is your plan if there are no strong offers in the first three weeks?
- What is your fee, what does it include, and how long is the holdover?
Credit Valley rewards sellers who explain their lot. A wide frontage, a ravine view or a quiet crescent away from the busy corridors can all justify a stronger price, but only if buyers see the proof. I like to put lot size, frontage and a short note on nearby planning in the first page of the listing package, so buyers stop guessing and start comparing.
How do commission and listing agreements work in Ontario?
RECO says the fee is agreed between you and the brokerage and is not set by RECO, any government or any real estate board. It can be a fixed amount, a percentage or both, but it cannot be based on the gap between list price and sale price. The expiry date must be clear on the first page, and the services you are paying for should be listed. If there is a holdover clause, RECO says there is no set length, so agree on it before you sign. Read my holdover clause guide first.
What are the red flags when choosing a Credit Valley agent?
- Comparable sales with no lot frontages listed.
- Promises about a garden suite or basement unit on a valley lot without checking the rules.
- No idea what is planned on Queen Street West or the corridors near you.
- A list price far above recent sales, with no written reasons.
- Pressure to sign a long agreement with a long holdover before you compare anyone.
- Not registered, or a recent discipline record, on RECO’s public register.
Should you hire a Credit Valley local or a GTA-wide agent?
Choose someone who knows Credit Valley’s enclaves and also understands buyers from across the GTA. In my experience, many people looking here are also weighing Mississauga to the south and other parts of west Brampton. My Brampton vs Mississauga 2027 comparison shows how the two cities differ on price and pace. For the community just north, see my guide to the best realtor in Mount Pleasant.
What to do next
- Find your survey and note your lot frontage and depth.
- Gather permits, second-unit registration and any rental licence papers.
- Ask whether your lot is regulated by the conservation authority before planning any work.
- Interview two or three agents with the same questions, and check each on RECO’s register.
- Before signing, confirm the fee, expiry date, holdover period and services in writing.
Need help with this? Talk to me.
I’m Jatin Dua, Broker of Record at RE/MAX Quantum Realty, and I’m the best agent to do this kind of work for you in Toronto and across the GTA. Over $100 million in GTA sales and 100+ families helped sell. Feel free to contact me any time: call or text 833-330-1925 or email [email protected].
Frequently asked questions
Who is the best realtor in Credit Valley, Brampton?
No public ranking can tell you who the best realtor in Credit Valley is, so judge agents on evidence. In 2027, choose one who compares your home with sales of similar lot frontage, knows the City’s updated Credit Valley plan, checks river and creek rules and second units, and is in good standing on RECO’s public register.
Where is the Credit Valley neighbourhood in Brampton?
Credit Valley is in southwest Brampton. The City’s secondary plan, updated in September 2026, bounds it by Mississauga Road and the Credit River to the west, Steeles Avenue West to the south, Chinguacousy Road to the east, and Bovaird Drive to the north. It covers about 1,176 hectares across parts of Wards 4 and 5.
What is the average house price in Credit Valley, Brampton?
There is no reliable public median for Credit Valley alone. For Brampton as a whole, TRREB MLS data via REALM shows a median detached price of $950,000 from January to October 2026, down 8.9% from 2025. Credit Valley homes vary with lot frontage and setting, so ask for comparable sales before you buy or sell in 2027.
Are house prices dropping in Brampton in 2026?
Yes. Brampton’s median detached price fell 8.9% to $950,000 from January to October 2026, and it is about 15.7% below the same months of 2024, per TRREB MLS data via REALM. Detached sales rose 9%, so Credit Valley sellers heading into 2027 will find active buyers who expect sharp pricing.
How wide are the lots in Credit Valley, Brampton?
It depends on the area. Brampton’s Credit Valley plan sets a minimum 15-metre (50-foot) frontage in Upscale Executive Housing areas, with a range up to 26 metres (85 feet) and beyond, and 21 metres (70 feet) or more in anchor areas. Other parts of Credit Valley are not held to those frontages, so check each comparable sale in 2027.
Will there be condos built in Credit Valley, Brampton?
Some taller buildings are allowed on main roads. Brampton’s updated Credit Valley plan permits mid-rise buildings of 5 to 12 storeys along Queen Street West and on Mississauga Road, Chinguacousy Road and Bovaird Drive West. Interior streets stay mostly low-rise, up to three storeys. Check the City’s planning notices before you buy in 2027.
Can I add a basement apartment to a house in Credit Valley?
Usually, if you register it. Brampton allows up to three units on a property, counting the main house, and every additional unit must be registered with the City. Units are not allowed in floodplain areas or open space zones, which can affect some Credit Valley lots near the river. Confirm the rules for your address in 2027.
How much commission does a realtor charge in Brampton?
There is no standard rate in Brampton. RECO says commission is negotiated between you and the brokerage and is not fixed by RECO, any government or any real estate board. It can be a flat fee, a percentage or both. Compare at least two written proposals before you list a Credit Valley home in 2027.
Sources
- City of Brampton: Credit Valley Secondary Plan (Area 12), office consolidation September 2026
- City of Brampton: Public notice, Credit Valley Secondary Plan Review, Area 45, Wards 4 and 5 (May 2025)
- insauga: Will this Brampton neighbourhood see new residential developments? (7 Mar 2019)
- Credit Valley Conservation
- City of Brampton: Additional Residential Units
- City of Brampton: Residential Rental Licensing
- TRREB Market Watch, October 2026
- RECO: Signing a contract with a real estate brokerage
Related reading
- Best Realtor in Lorne Park (Mississauga) for 2027: How to Choose
- Best Realtor in Port Credit (Mississauga) for 2027: How to Choose
- Best Realtor in Erin Mills (Mississauga) for 2027: How to Choose
- Best Realtor in Churchill Meadows (Mississauga) for 2027: How to Choose
About the author — Jatin Dua, Toronto and GTA real estate broker
I am Jatin Dua, Broker of Record and co-founder of RE/MAX Quantum Realty Inc., Brokerage, Unit 101, 799 The Queensway, Toronto. I work with buyers and sellers across Toronto and the GTA and have helped more than 100 families sell. Four-plus years of active GTA transactions and over $100 million in sales volume.
Reach me at [email protected] or 833-330-1925, or book a call.