
Published 2 November 2026 · By Jatin Dua, Broker of Record, RE/MAX Quantum Realty
The best realtor in Port Credit for 2027 knows the difference between selling a waterfront condo, a heritage-district house and a freehold home, and can prove recent local sales. Mississauga condo medians fell 9.3% to $485,000 (Jan–Oct 2026) with 42 average days on market, so insist on a written pricing and launch plan.
This guide is for anyone selling or buying in Port Credit in 2027, whether that is a condo by the lake, a house in the old village, or a freehold home a few streets north of Lakeshore Road. You will get real Mississauga market numbers, what makes Port Credit different, the questions to ask any agent, the red flags, and how commission and agreements work in Ontario.
What makes Port Credit real estate different?
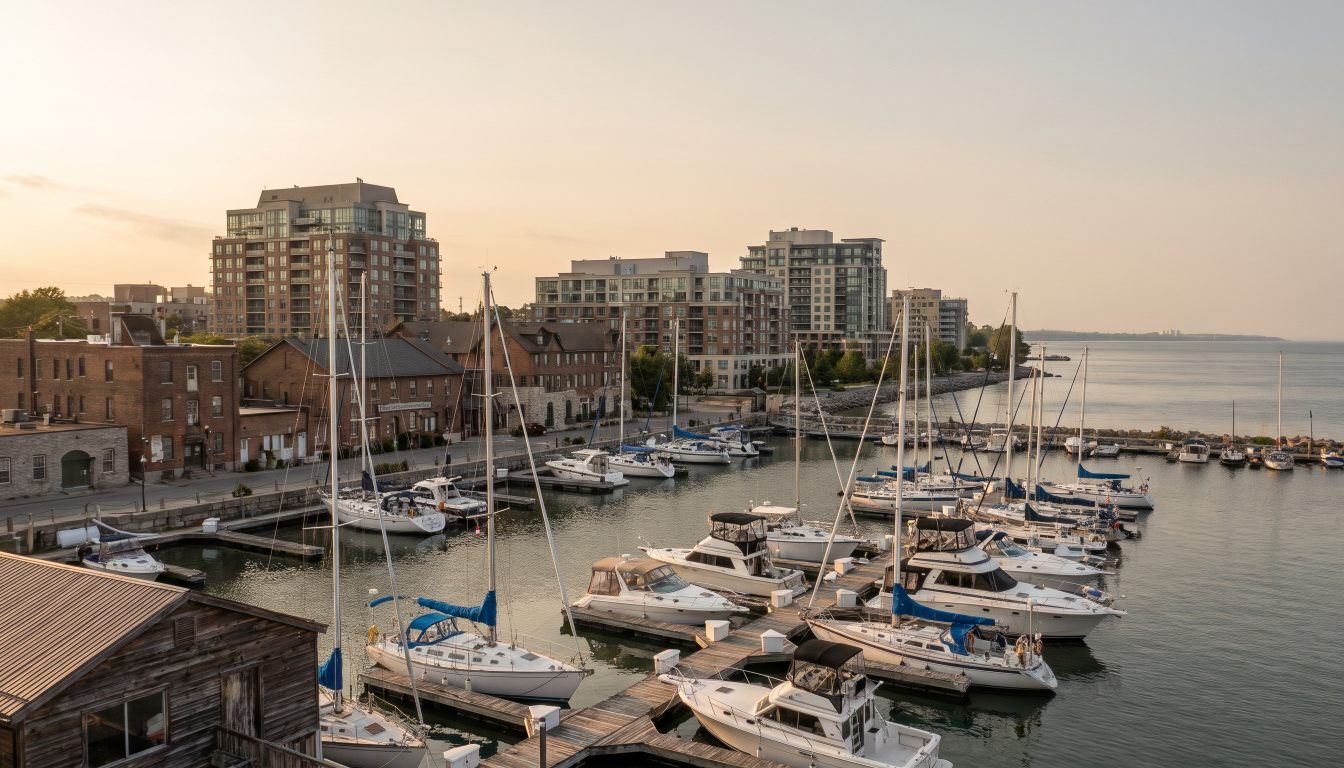
Port Credit sits where the Credit River meets Lake Ontario, in south-central Mississauga. It is often called the “village on the lake.” A village plan was laid out in the 1830s, the area became a town in the early 1960s, and it joined the City of Mississauga in 1974. The old harbour is now a marina.
That history leaves a market with several very different products side by side:
- A heritage village core. The Old Port Credit Village Heritage Conservation District was designated by the City of Mississauga in 2004 under the Ontario Heritage Act. It roughly covers the area between Lakeshore Road West and the lake, from Mississauga Road South to the Credit River. Homes there are mostly modest one-and-a-half-storey houses on the original street grid.
- Condos. Much of Port Credit’s recent population growth has come from condominium buildings, alongside the older homes.
- Large new waterfront supply. The former Imperial Oil refinery lands (the refinery ran from 1932 to 1985) have been cleaned up for a 72-acre community planned for up to 3,900 homes over ground-floor retail. My guide to Brightwater in Port Credit covers what has been confirmed.
- A transit hub. Port Credit GO Station, at 30 Queen Street East, is on the Lakeshore West line. It is also the planned southern end of the Hazel McCallion LRT along Hurontario Street.
Selling a two-bedroom condo, a heritage-district cottage and a large detached home north of Lakeshore are three different jobs. The right agent knows which job yours is.
What are Port Credit home and condo prices doing in 2026?
TRREB does not publish a reliable public median for Port Credit alone, so I will not invent one. Here is the verified picture for Mississauga as a whole, which shows the direction the market is moving.
| Mississauga property type | Median sold price, Jan–Oct 2026 | Same period 2025 | Change | Average days on market 2026 (2025) |
|---|---|---|---|---|
| Detached | $1,225,000 | $1,300,000 | −5.8% | 31 (28) |
| Semi-detached | $885,000 | $955,000 | −7.3% | 26 (22) |
| Freehold townhouse | $880,000 | $950,000 | −7.4% | 29 (23) |
| Condo townhouse | $689,300 | $750,000 | −8.1% | 37 (30) |
| Condo apartment | $485,000 | $535,000 | −9.3% | 42 (37) |
Source: TRREB MLS data via REALM, January–October 2026 vs the same period of 2025, City of Mississauga as a whole. Port Credit is not reported separately; waterfront and heritage homes can differ a lot from these medians.
For Port Credit, the condo line matters most. Mississauga condo apartment medians fell 9.3% to $485,000, and the average condo took 42 days to sell, up from 37 days in 2025 and 31 in 2024. There were 813 active condo apartment listings in Mississauga at the end of the period. Condo sellers are competing for attention, and new waterfront supply adds to that.
Detached homes held up better, down 5.8% with sales slightly higher than in 2025. Borrowing costs also matter: the Bank of Canada raised its policy rate to 2.50% on 28 October 2026 and big-bank prime rose to 4.70%. Any rate forecast for 2027 is just that, a forecast.
What should a Port Credit realtor understand that others might miss?
How to price a condo against new supply
When there are many similar units for sale, small details decide who sells first: the floor plan, the view, parking and locker, maintenance fees, and the building’s reserve fund. A strong agent compares your unit to what is actively listed in your building and nearby, not only to what sold last spring. For building-by-building context, see my guide to buying a Port Credit condo.
Heritage district rules
If a house is inside the heritage conservation district, buyers who plan additions or a rebuild need to know that the district has its own plan, and new work must respect the area’s scale, setbacks, street grid and trees. A good agent tells buyers to check what is allowed with the City’s heritage planning staff before firming up.
Planning limits along Lakeshore Road
Mississauga’s Port Credit Local Area Plan treats Lakeshore Road as a main street and generally keeps frontages along Lakeshore Road West to four storeys. Buyers who hear that “a tower is coming next door” should look at the actual plan and any active applications, not rumours.
Transit timing, honestly
The Hazel McCallion LRT will run about 18 km with 19 stops from Port Credit GO to Brampton. As of 2026, Metrolinx has not published an opening date. An honest agent will not use a firm LRT date to justify a price.
Instant Home Valuation
What’s your home
worth today?
Answer six quick questions and get an instant value range built from current Toronto & GTA sale data — property type, size, condition, lot and location all weighted the way a real pricing conversation weighs them. Takes about ninety seconds.
Reading recent GTA sale data…
Building your estimate
Estimated market value
—
$0–$0
Most likely value $0 · roughly $0 per square foot
What moved the number
Starting from the area baseline for your property type, here’s what each answer added or subtracted.
Market context
Recent local averages for comparison.
—
A range is a starting point.
A strategy is what sells.
This model doesn’t know that your neighbour’s identical semi went $80,000 over asking last month, or which two upgrades actually pay back in your area. That conversation is free and takes twenty minutes.
What questions should you ask a Port Credit realtor before you hire them?
- How many Port Credit condos or houses have you sold, or helped buyers buy, in the last two years? Can I see them on MLS?
- For my unit or home, what are the closest recent sales, and what is listed right now that a buyer will compare it to?
- How will you make my condo stand out when there are many similar units for sale?
- If my home is in the heritage district, what do buyers usually ask, and how will you answer?
- Will you be my designated representative, or will the whole brokerage represent me?
- What is your fee, what does it include, and how long is the holdover period?
- How do you handle offers if your brokerage also represents a buyer?
Check each agent on RECO’s public register. It confirms registration and shows enforcement activity, such as discipline decisions, from the past five years. If you are a buyer, ask the same questions in reverse: how many Port Credit buildings they know well and how they review condo documents with your lawyer.
For a Port Credit condo in 2027, preparation beats price cuts. Clean, well-lit photos, a clear floor plan, and a seller who has the building documents ready can shorten the wait more than a small reduction. Ask every agent you interview to show you exactly how they would launch your listing in its first week.
How do commission and listing agreements work in Ontario?
Commission in Ontario is negotiable. RECO says you and the brokerage agree on the fee, and it is not fixed or approved by RECO, the government or real estate boards. It can be a flat amount, a percentage of the sale price, or both. It cannot be based on the difference between the list price and the sale price.
Every representation agreement must be in writing. Before you sign, check:
- Expiry date: shown clearly on the first page. There is no standard length.
- Holdover period: how long after expiry a fee can still be owed. There is no standard length, so agree on it up front.
- Services: anything you expect, like staging advice, video or floor plans, should be written in.
- Representation type: brokerage or designated representation, which has been available since 1 December 2023.
- How the fee changes: for example, if the other side pays part of it.
For more detail, read Ontario’s representation agreement rules and my guide to commission in Ontario.
If the same agent or brokerage represents both you and the other side, that is multiple representation. It needs written disclosure and written consent from everyone, and you can refuse. If you agree, the agent cannot advise you on price or terms. With one brokerage often holding several listings in the same Port Credit building, ask early how they would handle it.
What are the red flags when choosing a Port Credit agent?
- A price with no comparables. If an agent cannot show you recent sales and current competing listings, the number is a guess.
- “We’ll just list it and see.” In a market where condos average more than 40 days to sell in Mississauga, a plan matters.
- No questions about your building. A good condo agent asks about fees, special assessments, rules on rentals and pets, and recent building work.
- Hype about transit or development. Watch for firm promises about LRT dates or future values.
- Pressure to sign a long term. A long agreement with a long holdover and no clear exit favours the agent.
- Not registered or a recent discipline record. Always check the register.
Should you hire a Port Credit local or a GTA-wide agent?
The best answer is an agent who has both. Local knowledge helps with the details: which buildings face the lake, how the heritage district works, and which streets buyers prefer. GTA-wide experience matters because many Port Credit buyers are comparing it with Toronto’s waterfront condos, Etobicoke’s lakeshore, Oakville or other parts of Mississauga. An agent who works across those markets can position your home against the real alternatives and reach buyers where they live now.
Buyers benefit the same way. If you are deciding between Port Credit and other lakeside areas, an agent who knows each one can tell you honestly what your budget buys in each. My 10 things no one tells you about Port Credit is a good place to start.
What to do next
- Decide what you are really selling or buying: a condo, a heritage-district home or a freehold house outside the district.
- Get a value range based on recent sales and current competing listings, not just an online estimate.
- Interview two or three agents with the same questions, and check each one on RECO’s public register.
- Gather your documents early: for condos, the building’s records and fees; for houses, permits and any work done.
- Before signing, review the expiry date, holdover period, services, fee and representation type in writing.
Need help with this? Talk to me.
I’m Jatin Dua, Broker of Record at RE/MAX Quantum Realty, and I’m the best agent to do this kind of work for you in Toronto and across the GTA. Over $100 million in GTA sales and 100+ families helped sell. Feel free to contact me any time: call or text 833-330-1925 or email [email protected].
Frequently asked questions
Who is the best real estate agent in Port Credit?
There is no official ranking of agents in Port Credit, so judge by evidence. Ask each candidate for recent Port Credit sales on MLS, the closest comparable sales and competing listings for your property, and a written launch plan. Then check them on RECO’s public register. In 2027, the best agent is the one whose plan fits your exact home.
How much is a condo in Port Credit in 2026?
No reliable public median exists for Port Credit condos alone. Across Mississauga, the median condo apartment sold for $485,000 from January to October 2026, down 9.3% from the same period of 2025, according to TRREB MLS data via REALM. Prices vary widely by building, view and size, so ask for building-level comparable sales.
How long does it take to sell a condo in Port Credit?
Mississauga condo apartments averaged 42 days on market from January to October 2026, up from 37 days in 2025 and 31 days in 2024, based on TRREB MLS data via REALM. Port Credit results vary by building, view and price. In 2027, a well-priced, well-presented unit will usually beat the average.
Is Port Credit a heritage district?
Part of it is. The Old Port Credit Village Heritage Conservation District was designated by the City of Mississauga in 2004 under the Ontario Heritage Act. It covers much of the original village between Lakeshore Road West and the lake. Buyers planning changes in 2027 should check what is allowed with the City’s heritage planning staff first.
When will the Hazel McCallion LRT open in Port Credit?
No official opening date had been published in 2026 reporting. The LRT will run about 18 km with 19 stops from Port Credit GO Station to Brampton, but Metrolinx has not published a completion date. Do not let anyone use a firm LRT date to justify a Port Credit price in 2027.
What commission do realtors charge in Port Credit?
There is no standard rate in Port Credit or anywhere else in Ontario. RECO says commission is agreed between you and the brokerage and can be a flat fee, a percentage or both. It cannot be based on the gap between list price and sale price. Ask every agent exactly what services their fee includes for 2027.
Can I cancel a listing agreement in Port Credit?
It depends on what your agreement says. RECO advises that an agreement should list every way it can end and any penalties or costs. Before you sign in 2027, read the cancellation terms, the expiry date and the holdover period, and ask the brokerage to put any promised early-exit option in writing.
Should I use the listing agent to buy a Port Credit condo?
You can, but it creates multiple representation if the agent or brokerage also acts for the seller. Ontario rules require written disclosure and written consent from everyone, and you can refuse. If you agree, the agent cannot advise you on price or terms, so many buyers prefer their own agent in 2027.
Do I need a Port Credit specialist or a GTA-wide realtor?
The strongest choice usually has both. Local knowledge helps with building differences, the heritage district and street-by-street pricing in Port Credit. GTA-wide experience helps reach buyers comparing Port Credit with Toronto’s waterfront, Etobicoke or Oakville, and helps buyers compare those options honestly before they commit in 2027.
Sources
- Port Credit (Wikipedia)
- Heritage Guide: Old Port Credit Heritage Conservation District
- City of Mississauga: Port Credit Local Area Plan (MOP 2051)
- Port Credit GO Station (Wikipedia)
- Hurontario LRT (Wikipedia)
- RECO: Signing a contract with a real estate brokerage
- RECO: Understanding multiple representation
- RECO: Make sure your real estate agent is registered
Related reading
- Best Realtor in Lorne Park (Mississauga) for 2027: How to Choose
- Best Realtor in Erin Mills (Mississauga) for 2027: How to Choose
- Best Realtor in Churchill Meadows (Mississauga) for 2027: How to Choose
- Best Realtor in Streetsville (Mississauga) for 2027: How to Choose
About the author — Jatin Dua, Toronto and GTA real estate broker
I am Jatin Dua, Broker of Record and co-founder of RE/MAX Quantum Realty Inc., Brokerage, Unit 101, 799 The Queensway, Toronto. I work with buyers and sellers across Toronto and the GTA and have helped more than 100 families sell. Four-plus years of active GTA transactions and over $100 million in sales volume.
Reach me at [email protected] or 833-330-1925, or book a call.