

Published 25 September 2026 · By Jatin Dua, Broker of Record, RE/MAX Quantum Realty
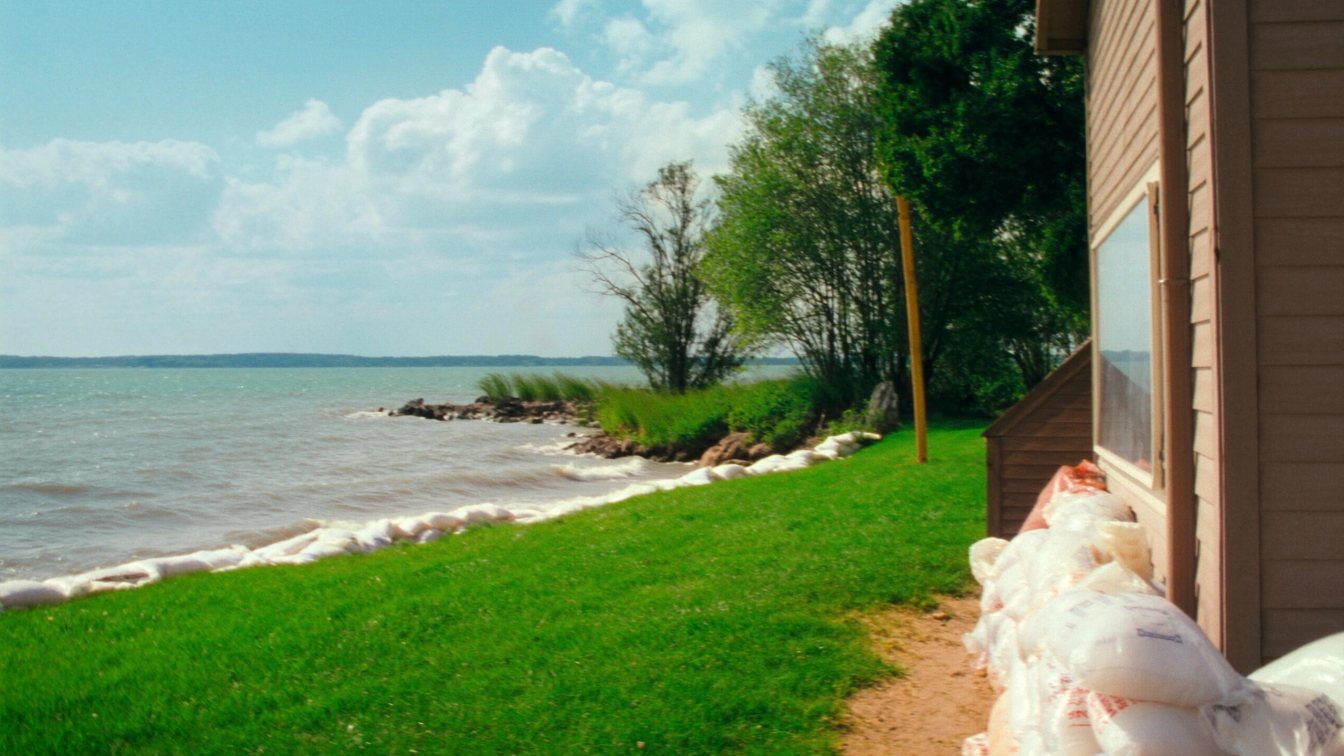
A standard Canadian home insurance policy does not cover flooding. Overland water coverage — for water entering from outside through doors, windows and foundations after heavy rain, snowmelt or a rising lake — is an optional add-on that only became widely available after 2015. The Insurance Bureau of Canada reported in July 2026 that about 94% of Canadian homes can now buy it, but roughly 850,000 still cannot, and a share of those are on the Lake Ontario shoreline. The federal government’s national flood insurance program for high-risk homes, promised in 2019 and funded at $450 million, missed its April 2026 target and has no confirmed launch date. For a waterfront buyer the rule is simple: get a written insurance quote on the specific address, including overland water, before you waive your conditions. If no insurer will write it, that is the market telling you something about the lot.
What your standard policy covers, and what it does not
A typical Canadian homeowner policy covers water damage from inside the house: a burst pipe, a failed water heater, an overflowing tub. It does not cover water that comes in from outside because of weather or a rising lake. That exclusion surprises buyers every year, usually after the basement has filled.
Three add-ons fill the gap, and they are separate products:
- Sewer backup covers water forced back up through drains when municipal sewers are overwhelmed. Widely available for years.
- Overland water covers water entering from outside through doors, windows, cracks and foundations after heavy rain, snowmelt, or an overflowing river or lake. Available in Canada only since 2015, and not to every address.
- Groundwater / seepage, where offered, covers water rising through the foundation from saturated ground. Often bundled with overland water, sometimes excluded.
On a lakefront lot you want all three, and you want to read the definitions, because the difference between “overland water” and “storm surge” or “coastal flooding” is where claims get denied. Some policies exclude water from a body of water specifically. Ask.
Where Canada stands in 2026
| Figure | Value | Source |
|---|---|---|
| Homes eligible for overland flood coverage | About 94% of residential properties | IBC, July 2026 |
| Homes that still cannot get it | Roughly 850,000, down from about 1.5 million seven years earlier | IBC, July 2026 |
| Insurers offering overland flood | More than 30 | IBC |
| Take-up among eligible homes | 26% in 2017 to 71% in 2023 | IBC |
| Federal national flood insurance program | Promised 2019; $450 million over five years; April 2026 target missed; no confirmed date as of mid-2026 | IBC via Insurance Business |
The 850,000 matter to this article because they are, by definition, the highest-risk addresses in the country — and shoreline lots that sit low or flood repeatedly are among them. An insurer’s refusal is not bureaucracy. It is a risk assessment you get for free.
Why Lake Ontario is a flood question at all
People think of flood insurance as a river problem. On the Lake Ontario shore the lake itself is the river. The lake’s level is regulated under the International Joint Commission’s Plan 2014 through the Moses-Saunders dam, but regulation smooths extremes rather than preventing them. In 2017 the lake reached 75.93 metres above sea level, inundating the Toronto Islands. In 2019 it set a new record of 76.03 metres. Two records in three years is not a pattern a buyer should assume will not repeat.
Low-lying shoreline lots — bay-front properties, beach-level houses, anything where the main floor is close to lake level — are the ones that feel a high-water year. Bluff-top houses generally do not flood; their risk is the ground, not the water, and that is a different insurance conversation covered in the Bluffs guide.
The order of operations that protects you
- Before you offer: ask the listing agent for the conservation authority’s flood hazard mapping for the address. TRCA, Credit Valley Conservation, Conservation Halton and Central Lake Ontario Conservation all publish regulated-area and flood mapping.
- In the offer: include an insurance condition — not just financing. The condition should let you walk if you cannot obtain coverage, including overland water, at a premium you accept.
- During the condition period: get a written quote from at least two insurers on the exact address. Ask each specifically whether overland water is available and whether water from a lake or bay is excluded.
- Ask the seller in writing: has water ever entered the home, and has any insurance claim been made for water damage? Ontario sellers must not misrepresent, and a written question creates a record.
- Only then waive the condition.
What you can do to the house
Insurers price the house as well as the lot. Backwater valves, sump pumps with battery backup, disconnected downspouts and graded landscaping all lower the risk and sometimes the premium. The City of Toronto’s Basement Flooding Protection Subsidy, for work completed on or after 12 November 2025, pays 80% of invoiced cost up to a total of $6,650 per property for eligible measures — backwater valves, sump pumps and related work — on single-family homes and small multiplexes with disconnected downspouts. Other municipalities have their own programs. Read the Toronto subsidy guide for the details.
None of that changes the lot’s elevation. If the main floor is at lake level, engineering slows water; it does not stop a record year.
The federal program: do not wait for it
Ottawa has promised a national flood insurance program for high-risk homes since 2019. It carries $450 million over five years and was most recently targeted for an April 2026 launch, which passed without a program. As of mid-2026 there is no confirmed delivery date. It may arrive; it may arrive with premiums that reflect the risk; it may not arrive in a form that helps a specific lot. Buy as if it will never exist. If it does, that is a bonus you did not pay for.
What this means for price
An uninsurable or barely insurable lot is worth less than an insurable one, and the market has been slow to price that in because most buyers ask about insurance after they commit. If you are the buyer who asks first, you either walk away from a lot others will overpay for, or you buy it at a price that reflects the answer. Either outcome is better than finding out in the first high-water spring.
The takeaway
Standard home insurance does not cover flooding. Overland water coverage is optional, still unavailable to about 850,000 Canadian homes, and the federal backstop has no launch date. On any low-lying Lake Ontario lot: get the conservation authority’s flood mapping, write an insurance condition into the offer, obtain written quotes that name overland water on the exact address, ask the seller in writing about past water, and only then waive. An insurer’s no is the cheapest inspection you will ever get.
Where I fit
I am a real estate broker, not an insurance adviser, and I will tell you when a question is one for your broker rather than me. What I do is make sure the insurance condition is in the offer and the quote is in hand before you waive, because I have watched buyers skip that step. Run the estimator below to see what your current home is worth, or book a call.
Free tool — AI home value estimator
Instant Home Valuation
What’s your home
worth today?
Answer six quick questions and get an instant value range built from current Toronto & GTA sale data — property type, size, condition, lot and location all weighted the way a real pricing conversation weighs them. Takes about ninety seconds.
Reading recent GTA sale data…
Building your estimate
Estimated market value
—
$0–$0
Most likely value $0 · roughly $0 per square foot
What moved the number
Starting from the area baseline for your property type, here’s what each answer added or subtracted.
Market context
Recent local averages for comparison.
—
A range is a starting point.
A strategy is what sells.
This model doesn’t know that your neighbour’s identical semi went $80,000 over asking last month, or which two upgrades actually pay back in your area. That conversation is free and takes twenty minutes.
Frequently asked questions
Does home insurance cover flooding in Ontario?
Not by default. Standard policies exclude water entering from outside. Overland water coverage is an optional add-on, available only since 2015 and not to every address; sewer backup is a separate add-on.
Can every waterfront home get flood insurance?
No. The Insurance Bureau of Canada reported in July 2026 that about 94% of Canadian homes can access overland flood coverage, leaving roughly 850,000 that cannot. Low-lying shoreline lots are among the addresses most likely to be refused.
Is there a government flood insurance program in Canada?
Not yet. A national program for high-risk homes was promised in 2019 with $450 million over five years, missed an April 2026 launch target, and had no confirmed delivery date as of mid-2026.
How high has Lake Ontario risen?
The lake set a record of 76.03 metres above sea level in 2019, beating the 2017 record of 75.93 metres. Both years brought shoreline flooding, including on the Toronto Islands.
What should I put in my offer on a waterfront home?
An insurance condition separate from financing, allowing you to walk if you cannot obtain coverage including overland water at a premium you accept. Then get written quotes on the exact address before waiving.
Does the Toronto basement flooding subsidy apply to waterfront homes?
If the home is an eligible single-family, duplex, triplex or fourplex in Toronto with disconnected downspouts, yes. For work completed on or after 12 November 2025 it pays 80% of eligible costs up to $6,650 per property. It reduces risk; it does not raise the lot.
Do bluff-top homes need flood insurance?
Rarely for flooding; their risk is erosion and earth movement, which standard policies also exclude but for different reasons. Ask the insurer about both if the lot is near any edge.
Sources
- Insurance Business Canada, 24 July 2026 — 94% of Canadian homes can access overland flood insurance, IBC finds — all insurance figures and federal program status
- CBC News — Lake Ontario water levels reach record (2019) — 76.03 m and 75.93 m
- International Joint Commission — 2017 and 2019 high water events — regulation and causes
- City of Toronto — Basement Flooding Protection Subsidy Program — 80%, $6,650 cap, 12 Nov 2025
- TRCA — Flood risk mapping — hazard mapping
Related reading
- Oshawa and Clarington lakefront homes
- Riverfront and ravine lots in the GTA
- Hamilton Beach Strip and Burlington Beachway
- Waterfront House Due Diligence in Ontario
- Financing and Insuring a Waterfront House in the GTA
- Stoney Creek Lakefront Homes
- Toronto basement flooding subsidy
- Frenchman’s Bay, Pickering
- Scarborough Bluffs: buying on the edge
- Landlord insurance in Ontario
- What a home inspection does not cover
About the author — Jatin Dua, Toronto and GTA real estate broker
I am Jatin Dua, Broker of Record and co-founder of RE/MAX Quantum Realty Inc., Brokerage, Unit 101, 799 The Queensway, Etobicoke. I work with buyers and sellers across Toronto and the GTA, with deep local knowledge of the west end and the Lake Ontario shoreline. Four-plus years of active GTA transactions and over $100 million in sales volume. Every market figure here comes from TRREB’s published tables and every rule from the regulator or the legislation, so you can check all of it without asking me.
Reach me at connect@jatindua.com or 833-330-1925, or book a call.